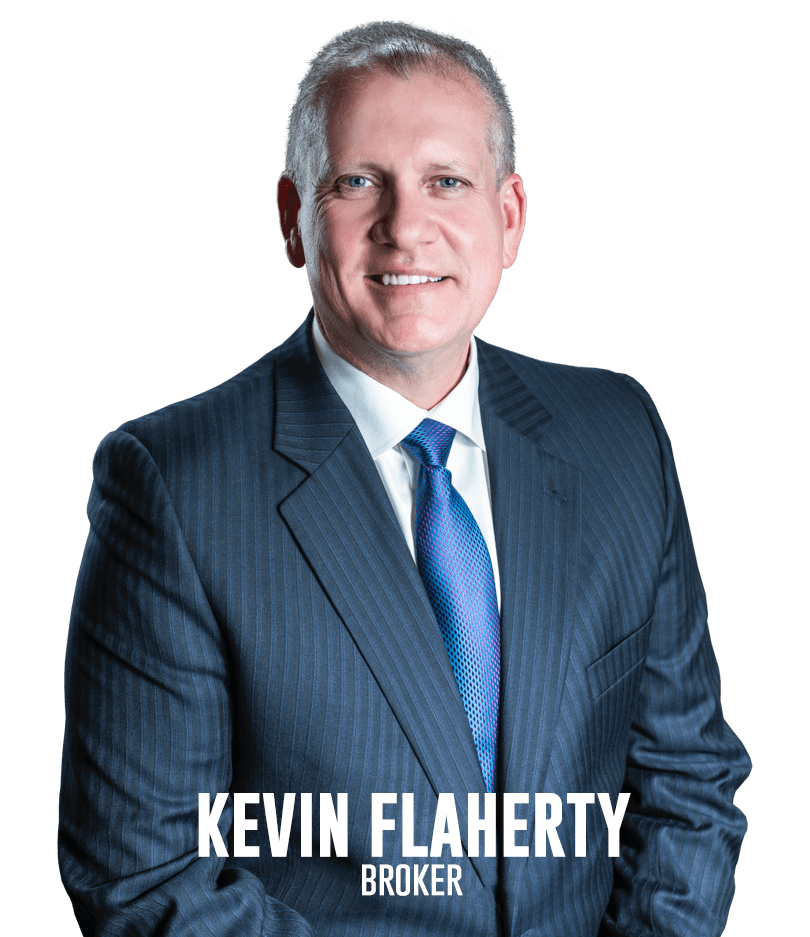
Kevin Flaherty, real estate broker, smiling in a professional suit with a blue tie, representing the Flaherty Team.
Kevin Flaherty, top 1% Orangeville realtor for 10+ years, providing free no-obligation home value opinions — call 226-270-6433
Kevin Flaherty Home Selling System Team branding graphic featuring the text ‘Kevin@Flaherty.ca
’ and toll-free phone number 1-877-352-4378
Graphic with the text ‘Online Showings – Get Your Home Sold Faster & For More!’ promoting Video Narrated VR animated online showings for faster real estate sales
Real estate marketing graphic showing a house with a ‘SOLD!’ sign promoting access to sold listings and property information, with a yellow ‘Click Here’ button offering access similar to a REALTOR.
VR floor plan of a home with oversized camera, video camera, and microphone graphics representing high-quality real estate photography, and video narrated VR animated online showings for advanced property marketing.
Flaherty Team logo with Kevin@Flaherty.ca featuring "Flaherty" in bold text, "Home Selling System Team" below, emphasizing real estate services
Graphic with the text ‘Online Showings – Get Your Home Sold Faster & For More!’ promoting Video Narrated VR animated online showings for faster real estate sales

ERIN · NEGOTIATED FEES · ACTUAL COSTS · A CLEARER BUDGET

Costs of Selling a Home in Erin: Plan Your Net Funds

The cost of selling an Erin home depends on the negotiated service agreement, actual legal and lender amounts, chosen preparation, moving arrangements and property-specific needs. Build an itemised budget that separates selling expenses from mortgage principal repayment, closing charges from credits, and already-paid costs from amounts still to fund. Kevin Flaherty can help organise the selling plan alongside your lawyer, lender and tax adviser; the sale price and estimated funds are not guaranteed.

Five Questions Before Budgeting for Your Sale

What Costs Should I Include?

Review negotiated commission and applicable HST, legal/disbursement bills, actual lender charges, chosen preparation, inspections/records, moving and other applicable costs. Mortgage principal repays debt; it is separate from selling expenses. Closing credits and any tax reserve need separate treatment.

What Should I Ask a Lawyer About Closing?

Request a written estimate including applicable taxes, disbursements and possible extras. Ask about actual title, payout, authority and adjustment questions, including which amounts are charges or credits and when they are paid.

Do I Need Well or Septic Investigations?

Review available records and actual requirements. Pre-listing work can be optional; a program, buyer, lender or insurer may have property-specific needs. Bacterial testing does not establish chemical safety or supply, and a pumping receipt does not certify septic condition or capacity.

Could Tax Affect the Amount I Keep?

Yes, depending on your facts. Principal-residence eligibility and reporting, rental/business use, land, ownership and GST/HST questions need suitable advice. HST on commission is separate from tax treatment of the property sale. A reserve is a planning amount, not a tax calculation.

How Can I Estimate Remaining Funds?

Use a supported sale-price range and the same cost categories across lower, middle and higher cases. Subtract principal, commission/HST, unpaid expense entries and closing charges; add credits. Deduct any entered reserve separately, without subtracting costs already paid a second time.

The Sale Price Is Not the Amount You Keep

A useful estimate starts with a supported sale-price range and an itemised cost list. Keep costs still to fund separate from already-paid expenses. Record actual quote dates, scope and tax treatment; identify anything already included in another bill or the lender payout.

On phones, scroll sideways within the table to read every column.

Selling Costs, Debt and Adjustments
CategoryWhat to IdentifyPlanning Check
Commission and HSTNegotiated fee and actual service agreement; the calculator uses a percentage.Show commission and 13% Ontario commission HST separately. Confirm structure, sharing and payment terms.
Legal and closing billActual fee, taxes, disbursements and possible extras.Ask your lawyer what applies and what is already included.
Mortgage principal / lender amountsPrincipal is debt repayment; fees, interest and penalties are distinct.Use a current payout quote and avoid duplicate deductions.
Preparation / moving / investigationsActual chosen scope, quotes, taxes and requirements.Separate optional work from obligations and costs already paid.
Closing adjustmentsCharges and credits can move the estimate in different directions.Use lawyer-reviewed figures; do not add the buyer deposit again.
Tax questions / reserveAdvice fees and any reserve are not the same as assessed tax.Get situation-specific advice on reporting, exemptions and timing.

Agree the Fee, Services and HST Before Comparing Proposals

Commission and any cooperating-brokerage arrangement are negotiated in the actual service agreement. No rate or split is required by this guide. Ask what is included, when payment is due and which work may be separately invoiced.

Commission and Tax Are Separate

For a taxable Ontario commission, show the fee and 13% HST on that fee separately. The property sale’s GST/HST status is a different question. The calculator uses a negotiated percentage, not a preset standard rate.

Compare Scope Without Assuming a Result

Discuss pricing advice, communication, media, measurements, offer review and actual costs. A higher or lower fee does not itself establish a better price, more qualified buyers or a better net result.

Check the invoice or agreement before counting media, staging or other services as another expense. If the fee is not a percentage, use the printable worksheet with the actual terms rather than force it into the calculator.

Get Written Legal and Lender Figures

Legal Bill and File Scope

Ask your lawyer for the actual estimate, applicable taxes, disbursements and possible extras. Review title, authority, access, survey and transaction questions that affect the file; avoid adding charges already included.

Principal and Payout Charges

Use a dated lender quote that separates principal, interest, fees and any penalty. Confirm validity and cash-back repayment. Principal repays debt and affects funds; it is not itself a selling expense.

Portability, Bridge and Timing

Discuss actual eligibility, terms, payment timing and costs with the lender before commitments. Portability, blending and bridge finance are not automatic. Include overlap or temporary housing only where relevant.

Choose Suitable Spending Before Booking Work

Compare actual condition, safety, information gaps, permissions, quotes, service inclusions and timing. Staging, cleaning, assessment and repairs all have costs and uncertain returns; there is no universal spending order or guaranteed payback.

Cleaning, Organisation and Light

Choose methods suited to the material and condition, including older finishes. Use safe assistance and access. Presentation must not hide known concerns or misrepresent room size, lawful use or included items.

Repairs and Significant Questions

Investigate leaks, moisture, persistent odours, damage, exposed wiring or unsafe structures with suitable help. Do not choose cosmetic fixes or pressure washing before understanding the cause and material.

Staging and Layout Explanation

Compare a targeted quoted plan with actual room needs and alternatives. Confirm how virtual staging is identified. No staging choice certifies condition or promises a higher price.

Inspection Scope and Workable Access

Distinguish optional preparation from actual requirements. Agree suitable professionals, safe access, scope and costs. Respect occupants, animals, privacy and tenancy/notice obligations.

Estimate Costs and Funds With Clear Arithmetic

Enter property-specific amounts. The required sale price and negotiated commission rate have no preset values; zero commission is valid. This percentage-based tool uses 13% Ontario commission HST and does not calculate tax on the property sale, capital gains or an actual lender payout.

Enter only costs still to fund in the unpaid fields, with applicable taxes included once. Use the separate previously-paid field for a budget record, excluding anything already in another entry. Separate mortgage principal from fees. A sale price already includes the buyer deposit; do not add it again.

Estimated funds = sale price − principal − commission − commission HST − unpaid expense entries − closing charges + closing credits. Planning funds after reserve = that amount − your reserve. Expense budget = commission/HST + unpaid expenses + previously paid expenses; it excludes principal, adjustments and the reserve.

Already-paid expenses are not deducted again from remaining funds. The estimate is not the lawyer’s exact closing payment, assessed tax, a guaranteed sale price or funds remaining after a next-home purchase. Payment timing, sale GST/HST and actual funding arrangements need separate review.

Budget for the Actual Property and Its Services

A community name does not establish municipal connections, private services or required investigations. Review actual land, buildings, condition, contracts, permitted uses and available records before budgeting for work.

Well and Septic

Review available records and actual program or transaction requirements. Bacterial tests do not establish chemical safety or supply, and pumping receipts do not certify the whole septic system or capacity. Agree safe access and suitable scope before booking work.

Surveys, Permissions and Access

Existing surveys, sketches, permits, fences and aerial imagery serve different purposes. Ask the lawyer/surveyor what is needed; verify actual permissions and legal access before ordering work or making use claims.

Equipment, Buildings and Seasonal Access

Review ownership/rental/finance contracts, actual provider obligations and transfer costs. Plan suitable authorised access to buildings and services; do not clear, grade, repair or enter unsafe spaces solely for presentation.

Review Tax Questions and Adjustment Direction

Principal Residence and Reporting

Eligibility, designation and sale reporting are separate questions. A fully exempt gain does not remove the reporting/designation requirement. Have actual use, ownership, residence and land reviewed before relying on an assumed outcome.

Sale GST/HST and a Planning Reserve

Most used residential housing sales are generally exempt, but exceptions can apply. That differs from HST on commission. A reserve entered with advice is not a tax calculation, an assessed amount or necessarily a payment due at closing.

Charges, Credits and Condominium Documents

Have your lawyer identify actual adjustments, deposit treatment and payment timing. For a condominium, agree who requests/pays for any status certificate and how it will be reviewed. A freehold townhome is not automatically a condo.

Confirm What Is Included Before Counting It Twice

Discuss the Listing Package

Confirm the actual offered pricing advice, media, measurements, listing copy, Video Narrated VR Animated Online Showings, communication and offer support in the written arrangement.

Confirm Separate Accounts

Legal/lender/tax advice, moving, storage, cleaning, repairs, staging or investigations may have separate arrangements. Use actual scope and bills rather than assume every possible item applies.

Review Before Spending

For major renovations, private-service work, surveys, full staging or cleanouts, compare suitable scope, obligations, cost and timing. No service package establishes a guaranteed financial return.

Compare Lower, Middle and Higher Cases Fairly

Use the same categories in each scenario. Hold cost assumptions consistent when isolating sale-price changes. If work scope, timing, lender terms or quotes change, record why rather than automatically pair a higher price with lower spending.

On phones, scroll sideways within the table to read every column.

Three-Scenario Planning Method
QuestionLower-Price CaseMiddle CaseHigher-Price Case
Sale priceSupported lower assumptionSupported middle assumptionSupported higher assumption
Expense categoriesUse the complete same listUse the complete same listUse the complete same list
Principal and lender quoteState amount/date/termsState amount/date/termsState amount/date/terms
Paid status / charges / creditsSeparate each directionSeparate each directionSeparate each direction
Changed assumptionWrite what changed and whyWrite what changed and whyWrite what changed and why

A CMA supports a listing-price opinion, not an appraisal or guarantee. Remaining sale funds are also different from the money left after a next-home purchase or move. Review actual funding needs before commitments.

Five Steps to a More Useful Selling-Cost Estimate

1. Choose a Supported Price Range

  1. Use relevant property comparisons alongside dated Erin market context.
  2. Treat a CMA as a listing-price opinion, not an appraisal or guaranteed price.
  3. Record the low, middle and high assumptions and evidence date.

2. Separate Costs From Debt

  1. Identify negotiated commission and applicable HST with actual service scope.
  2. Obtain legal and lender figures, separating principal from fees already in quotes.
  3. Record unpaid expenses, already-paid items and charges/credits separately.

3. Choose Suitable Preparation

  1. Compare safety, condition, assessment, permissions, costs and uncertain returns.
  2. Clarify optional inspections and actual private-service or transaction requirements.
  3. Confirm inclusions so media, staging or contractor services are not counted twice.

4. Review Tax and Ownership Questions

  1. Ask about principal-residence eligibility, designation and reporting.
  2. Review property-sale GST/HST, use, land and ownership with suitable advisers.
  3. Enter any reserve as a planning amount with its source and payment timing.

5. Compare the Three Cases

  1. Keep the same categories and state any changed scope or quote explicitly.
  2. Review estimated funds, unpaid obligations and next-home funding needs separately.
  3. Update estimates before commitments; the result is not an exact closing payout.

Your Erin Selling-Costs Workbook

Use the commission, closing, preparation, rural-property and three-scenario worksheets to record actual costs, questions and assumptions before booking work or choosing a listing date.

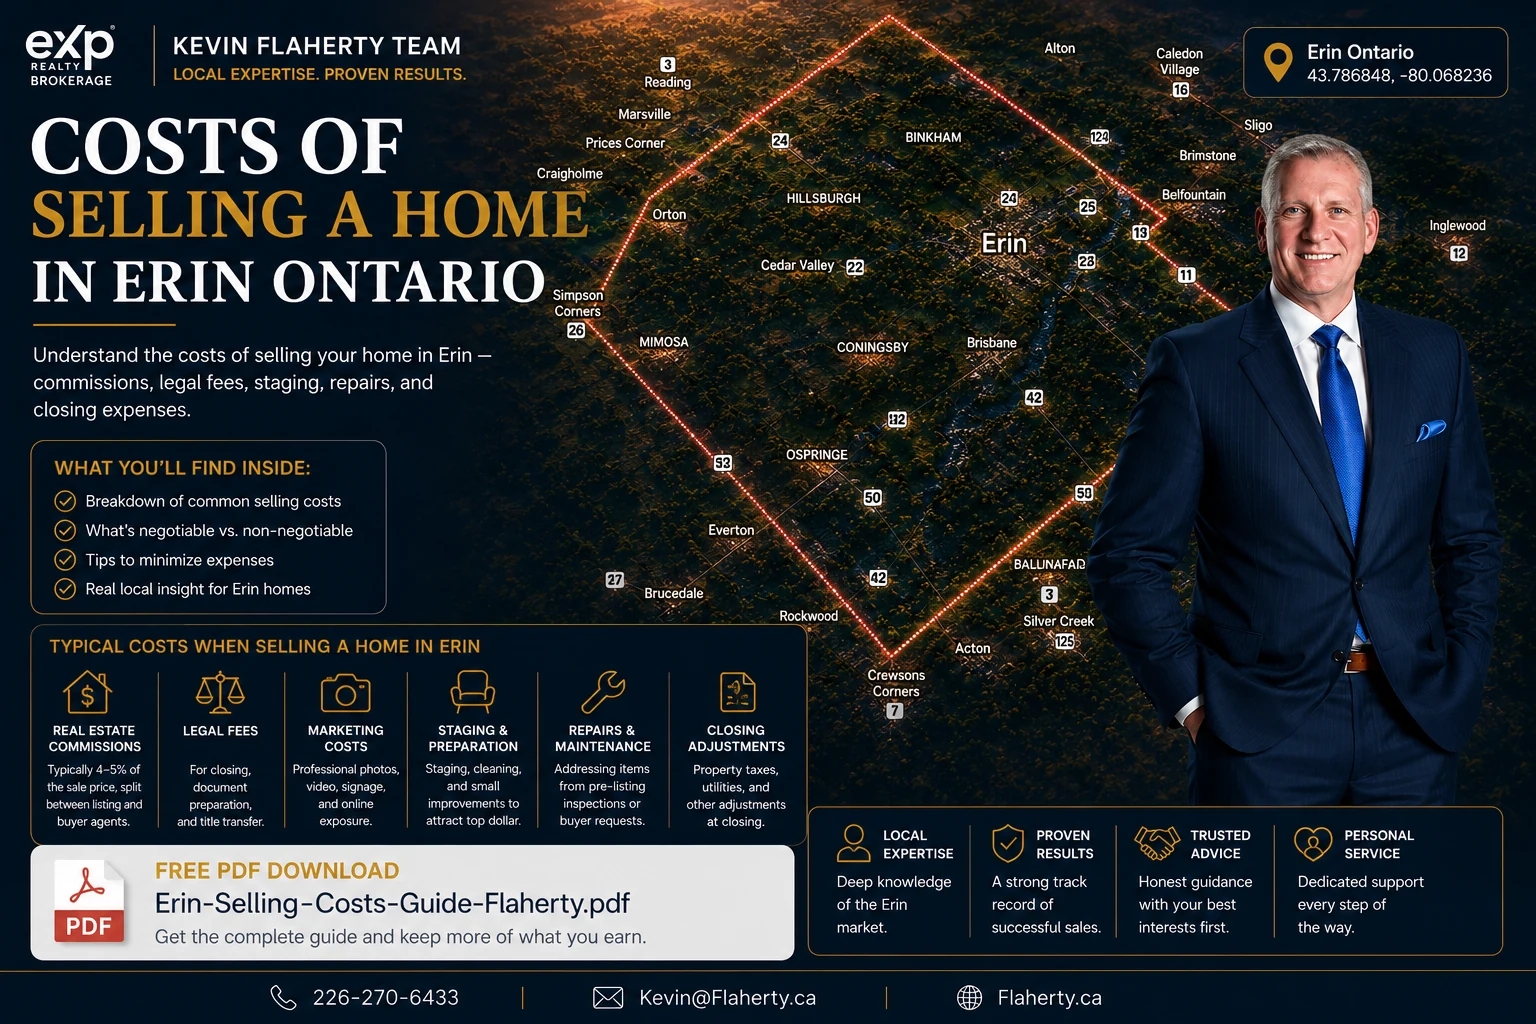
Erin selling costs artwork featuring Kevin Flaherty and an illustrative map; select to download the workbook

Commission is negotiated; the graphic’s illustrated rate is not a standard or required fee. The map is promotional artwork, not an official municipal boundary, survey or evidence of legal access.

See How Kevin Explains a Home Online

Essential Viewing Before You Plan the Sale

Prepare questions about inspection scope, representation, listing response and legal advice. Apply current property-specific guidance alongside these videos.

Pro Real Estate Tips - Home Inspection

Prepare questions about inspection scope, condition, records and safe access when comparing an existing home and proposed timing.

10 Questions to Ask Before You Hire a Realtor (Interview Guide)

Ask about representation, service scope, actual comparison evidence, communication and the agreement.

Pro Real Estate Tips - Why Didn't My House Sell?

Review activity, relevant alternatives and available feedback without assuming an unsold result proves a single cause.

Pro Real Estate Tips - How to Avoid Legal Mistakes When Selling Your House

Prepare transaction-specific questions about agreements, inclusions, disclosure and closing with your lawyer and Realtor.

Clients Describe Working With Kevin

These are individual experiences across Kevin’s service area, not verified Erin results or typical-outcome promises. A client’s account of an inspection recommendation or sale does not make that advice universal.

5/5 · RankMyAgent
From our first sit down with Kevin, his vast experience and professionalism were apparent. We interviewed several realtors and went with Kevin and his team because of his unique marketing strategy in this age of technology. Our home was advertised on many platforms. The 3-D virtual walk through the team created was exceptional. Potential buyers got a very accurate depiction of the property and home. Rooms were shown both furnished and unfurnished, and accurate blueprints with detailed room measurements were provided to assist interested shoppers. Kevin and his team answered any questions and requests in a timely manner and provided the sound advice needed to get our property sold for full asking price in a difficult market. What more could you ask for?

Melissa R. · RankMyAgent

5/5 · RankMyAgent
When we decided to sell our home we considered several agencies and agents. The expression 'you only get one chance to make a first impression' rings true in many applications, and none so important as selling your home. The 'first impression' we got from Kevin was that he knew his stuff. He was informed of trends in the housing market and what would sell and what hindered sales. Factors such as recent home sales, value of homes compared to what peoples hearts told them their worth all played into our decision to list with Kevin. His approach was not fast paced and had no high pressure tactics like that of a used car salesman of years gone by. His attitude was genuine and honest. He advised us of what we could do to increase the value of our home and what would make for a realistic sale. His years in the industry and his network of contacts played a key role in our home selling in a very short period of time, and over asking.

Peter Haddrell · RankMyAgent

Flaherty Team Google Profile: 5.0/5 from 61 Reviews · Checked November 3, 2026. Separately, Kevin Flaherty’s RankMyAgent Profile: 4.96/5 from 52 Verified Reviews · Checked November 3, 2026. Profile-wide figures, not Erin-only totals. View Review Sources.

Read More Client Reviews

About Kevin Flaherty

Kevin Flaherty, Broker with eXp Realty

Kevin Flaherty, Broker with eXp Realty

Kevin Flaherty brings 38 years of real estate experience and states that he has helped more than 2,500 families. These figures relate to his broader service area, not an Erin-only sample or a guaranteed financial result.

Kevin grew up near the Erin and Caledon Townline, and his family was connected to Erin through St. John Brébeuf Roman Catholic Church near downtown Erin. As a child, he rode his bike into Erin to visit friends and went skating at the Erin Community Centre and Arena. That personal connection informs his interest in the area; cost estimates still depend on the actual property and arrangements.

Discuss the actual scope, estimates, obligations and funding assumptions with Kevin and relevant advisers before booking work or making commitments. His office is at 170 Lakeview Court, Unit 3A, Orangeville; Erin is a service area.

View Professional and Review References

Frequently Asked Questions About Selling Costs in Erin

What Does It Cost to Sell a Home in Erin?

There is no fixed total in this guide. Build an itemised budget for negotiated commission/HST, actual legal and lender charges, chosen preparation, moving and applicable property-specific costs. Keep mortgage principal, adjustment credits/charges, paid items and tax reserves distinct.

How Much Is Real Estate Commission in Erin?

Commission and any cooperating-brokerage arrangement are negotiated through the actual service agreement; no rate or split is required by this guide. Confirm inclusions, separate charges, payment terms and applicable HST before comparing proposals.

Do Sellers Pay HST on Commission?

For an Ontario taxable commission, include 13% HST on the commission amount. The calculator shows commission and this tax separately. This does not determine whether the property sale itself is taxable or exempt.

What Legal Costs Should I Budget For?

Ask for a written estimate with applicable taxes, disbursements and possible extras. Actual title, lender, authority, registration or other questions can change the work. Confirm what is already included rather than add every possible charge automatically.

Should I Pay for Staging?

Compare actual room/layout needs, cost, service inclusions, safety and timing. A proportionate approach may be useful, but staging does not guarantee a premium or payback. Confirm how any virtual presentation is identified and that it does not misrepresent condition.

Which Repairs Are Worth Reviewing?

Start with condition and safety questions, suitable assessment, permissions and costs. Investigate leaks, moisture, persistent odours, damaged materials or wiring before cosmetics. Neither a major renovation nor a small repair has an automatic financial return.

Who Pays for Photography, Layouts and Marketing?

Confirm the offered package and costs in the actual service agreement. Discuss professional media, measurements, listing copy and Video Narrated VR Animated Online Showings with Kevin, including optional or separately invoiced items. Do not assume identical inclusions in every arrangement.

Are Pre-Listing Inspections Worth Paying For?

They may be useful for some properties, but are not universal requirements or guarantees against later questions. Agree relevant scope, suitable professionals, safe access and costs, separately from mandatory programs or actual buyer/lender/insurer requirements.

How Should I Budget for Well or Septic Questions?

Gather available records and known concerns, then discuss needed investigations and responsibility for payment. Bacterial water tests do not establish chemical safety or supply, and pumping receipts do not certify whole-system condition or capacity. Requirements depend on the property and actual transaction.

Which Mortgage Costs Could Apply?

Ask your lender about principal, interest, penalties, discharge/administration costs, cash-back repayment and quote validity. Portability, blending or bridge finance depend on the lender and terms. Do not deduct a fee twice if it is already part of a payout quote.

Can Capital Gains or Other Tax Apply?

The outcome depends on the property, use, ownership, residence and other facts. Principal-residence eligibility does not eliminate sale reporting/designation obligations. Rental, business, inherited-property, land and non-resident situations need suitable advice; the calculator does not calculate tax.

How Do Property-Tax Adjustments Affect Funds?

Your lawyer determines actual charges and credits under the agreement and accounts. A prepaid amount may create a credit; an amount owing may reduce funds. Use the appropriate direction rather than treat every adjustment as an expense or duplicate a bill already counted.

Who Requests and Pays for a Condo Status Certificate?

For an actual condominium, agree who will request and pay for it and when it will be reviewed with legal advice. Anyone can request one; do not assume all townhomes are condominium units or that the seller always bears the fee. Use current CAO guidance for the actual process.

Should I Order a New Survey?

Ask your lawyer and surveyor what is needed after reviewing existing material and actual boundary/access questions. A sketch, fence, aerial image or municipal map is not a legal survey or proof of access. Do not order new work solely from a generic checklist.

How Do I Estimate Net Funds Before Listing?

Use a supported price range and enter actual principal, negotiated commission, commission HST, unpaid expenses, charges and credits. Keep a tax reserve separate and do not deduct previously paid costs again. The result is a planning estimate, not the lawyer’s payout or funds remaining after a new purchase.

Which Costs Can Be Missed or Double-Counted?

Review commission HST, lender fees, bridge/temporary accommodation, storage, applicable investigations, actual adjustments and timing. Check whether items are already in another bill, payout quote or service package. Already-paid expenses belong in the budget record, not another deduction from remaining funds.

Should I Choose the Lowest Commission?

Compare actual fee, services, agreement terms, scope and risks. A higher or lower fee does not by itself establish a better sale price or net result. Avoid assuming that weak marketing or a guaranteed premium follows from a rate alone.

How Can Marketing Affect My Cost Decisions?

Understand which media and services are included and what they explain. Accurate presentation can help viewers understand the property; it does not verify financing or guarantee fewer showings, a premium or a better net result. Review additional spending against actual needs and uncertain returns.

Do Costs Differ Between Erin Village, Hillsburgh, Ospringe and Orton?

Actual services, condition, land, buildings, agreements and investigations matter more than the community label. Do not presume village connections or rural systems at an address. Verify the property and quotes rather than apply a fixed community cost profile.

Where Can I Find Current Erin Market Context?

Use the dated Erin real estate market report alongside relevant property comparisons when making a price decision. This cost guide stays focused on categories, actual quotes and arithmetic rather than reproducing quarterly statistics. Broad averages do not value an individual home.

Could a Faster Sale Reduce Expenses?

A different timeline can change interest, insurance, utilities, overlap or temporary housing costs, but the net effect depends on actual price, agreements and funding. Mortgage principal payments reduce debt rather than function entirely as an expense. Speed does not guarantee lower total costs or a better outcome.

What Should I Ask a Lawyer Before Listing?

Ask about fee/disbursement estimates and taxes, title and access, ownership/authority documents, lender instructions, adjustments, deposit treatment, disclosure and actual closing arrangements. Identify when tax or specialist advice is needed before commitments.

What Should I Ask a Realtor About Costs Before Signing?

Ask about negotiated remuneration, cooperation/sharing arrangements, HST, actual media/service scope, separate charges, preparation/investigation options, offer support and communication. Review estimates and risk without a promised price, speed or net return.

How Do I Start Planning Selling Costs?

Bring your price/timing questions, available records, lender information, move commitments and proposed spending. Build an itemised budget with Kevin and relevant advisers before booking work or making commitments. Record the source, date and assumptions for each estimate.
Explore Erin’s Community Settings

Community profiles help explain setting. Confirm the actual address, services, access and relevant comparisons rather than assume all homes in a community have the same features.

Town of Erin: Municipal Context

This is the Town of Erin municipal boundary, including its village and rural areas. It is not just Erin Village and does not define informal neighbourhoods, property boundaries, rights of access or an office location.

Boundary: Ontario municipal boundary data, Land Information Ontario. Contains information licensed under the Open Government Licence – Ontario. Basemap © OpenStreetMap contributors. Confirm current property-specific questions with the Town and suitable advisers.

Plan Your Erin Sale Before Choosing a Listing Date

Bring your timing goals, known concerns, available records and next-move questions. Review the actual property, suitable preparation, relevant evidence and workable terms before making commitments.

Contact form for home valuation inquiries, featuring a prominent "What's Your Home Worth?" heading and submit button, reflecting Flaherty Real Estate's services for homeowners.

170 Lakeview Court; Unit 3A
Orangeville, ON
L9W 5J7

Logo of eXp Realty Brokerage a real estate agency.

Not Intended To Solicit Properties Already Listed For Sale.

A HoneyCombHub.ca Web Site Solution

Copyright 2026 . All rights reserved.

Terms of Service/Privacy Policy