Legal fees and disbursements
$1,200–$2,000 planning allowance. Ask what the tax-inclusive quote covers, including mortgage discharge work, title and registrations. Retain your lawyer early enough for your transaction.

Shelburne seller cost guide · 2026
Selling costs depend on your agreed commission, legal and lender charges, preparation, moving and closing adjustments. Add 13% HST to the commission, then subtract the mortgage balance separately when estimating available proceeds. Use written quotes and your lawyer’s final statement; a net sheet is a planning estimate, not a guaranteed payout.
Use the following amounts to start a budget, not as measured Shelburne market fees or quotes. Not every item applies. Obtain tax-inclusive written quotes for services, confirm what your listing agreement includes and avoid counting an included service twice. Amounts outside these examples are possible.
An $800,000 hypothetical sale at 4.5% commission has $36,000 commission plus $4,680 HST. With $1,800 legal and discharge costs, $5,000 preparation, $3,000 moving and a $500 closing charge, the illustrated total is $50,980. Subtracting a separate $350,000 mortgage balance leaves an estimated $399,020, before any penalty, bridge financing or other unlisted charge.
Use the 13-page guide to compare fee examples, collect quotes and work through all five planning phases and 33 checklist items. It includes a printable net-proceeds worksheet and follow-up notes.

Use the following amounts to start a budget, not as measured Shelburne market fees or quotes. Not every item applies. Obtain tax-inclusive written quotes for services, confirm what your listing agreement includes and avoid counting an included service twice. Amounts outside these examples are possible.
On phones, scroll tables sideways to read every column.
| Cost category | Planning example | When it applies | What to confirm |
|---|---|---|---|
| Realtor commission | 3.5%–5% examples | As agreed | Negotiable rate or fee; confirm the total obligation and any amount toward the buyer’s brokerage fees in your agreement. No standard rate is assumed. |
| HST on commission | 13% of commission | On taxable commission | Calculated on the commission, not the home’s sale price. Other service quotes should identify their own taxes. |
| Legal fees and disbursements | $1,200–$2,000 | Obtain a quote | Planning allowance only. Confirm tax, disbursements, registrations and any separately charged lender discharge work. |
| Mortgage prepayment penalty | $0–$25,000+ | If applicable | Use a lender quote for the intended payout date. Your contract determines whether a penalty applies and how it is calculated. |
| Mortgage discharge fee | $200–$400 | If applicable | Lender fee example only. Confirm administrative and registration charges and whether any legal quote already includes them. |
| Home staging | $1,500–$5,000 | Optional | Choose the scope and quote for this home; no sale-price premium is assumed. |
| Pre-listing repairs | $500–$5,000 | Property-specific | Investigate actual defects, safety and permissions before choosing repairs. These amounts do not cover every project. |
| Professional photography | $300–$600 standalone example | Confirm inclusion | Kevin’s listing package includes professional photography. Confirm the written package; do not add an included service again. |
| Moving | $1,500–$8,000 | If needed | Local $1,500–$3,500 and long-distance $3,000–$8,000 are planning examples; get a quote for distance, volume, access and dates. |
| Deep cleaning | $300–$600 | If needed | A planning allowance for the actual scope; specialist remediation is a different service. |
| Landscaping / curb appeal | $200–$2,000 | If needed | Budget necessary maintenance and safe access; choose work for the season and property. |
| Property tax adjustment | $50–$500 illustration | Credit or charge | The lawyer calculates the adjustment from the bill and closing date. It can be outside this range. |
| Utilities / final accounts | $50–$300 illustration | As applicable | Confirm final readings, account balances and contractual adjustments; not every utility is adjusted through closing. |
| Bridge financing | $500–$3,000 illustration | If approved and needed | Obtain a lender quote for the amount, duration, interest and fees; it is not automatic when buying and selling. |
| Storage | $80–$600 illustration | Optional | At $80–$200 per month for one to three months, the arithmetic range is $80–$600; obtain an actual quote and include tax. |
| Pre-listing inspection | $400–$600 | If useful | Choose inspection scope with professional advice. A report does not certify all systems or prevent later conditions. |
| Condo status certificate | Up to $100 including tax | If applicable | Ontario’s standard statutory certificate charge is capped at $100 including tax. Confirm any separately requested service; ask your lawyer what is needed. |
The service-price ranges are budgeting illustrations, not supplier quotes or a TRREB fee survey. Ontario tax and standard status-certificate rules are linked in the research section.
Commission is negotiated. The rates below are comparison examples, not standard, required or quoted Shelburne rates. Review your brokerage’s services, your total fee obligation and any amount toward the buyer’s brokerage fees in the representation agreement.
| Sale price | 3.5% commission | 4.5% commission | 5% commission | HST on 4.5% | 4.5% plus HST |
|---|---|---|---|---|---|
| $600,000 | $21,000 | $27,000 | $30,000 | $3,510 | $30,510 |
| $700,000 | $24,500 | $31,500 | $35,000 | $4,095 | $35,595 |
| $800,000 | $28,000 | $36,000 | $40,000 | $4,680 | $40,680 |
| $900,000 | $31,500 | $40,500 | $45,000 | $5,265 | $45,765 |
| $1,000,000 | $35,000 | $45,000 | $50,000 | $5,850 | $50,850 |
Kevin’s listing package includes professional photography, Video Narrated VR Animated Online Showing production, MLS listing, social media marketing, buyer database outreach, staging consultation, pre-listing cost analysis, negotiation and closing coordination. Confirm the scope, inclusions and agreed fee in writing; do not count an included service as a second standalone expense.
Explore the Flaherty Home Selling System
On an $800,000 sale at 4.5%, commission is $36,000 and commission HST is $4,680, for $40,680 combined. Other service quotes should identify their own taxes. The tax treatment of the property itself is a separate question for your advisers.
Edit every starting amount to match your scenario. Use tax-inclusive amounts for other services; the tool adds 13% HST only to commission. Split the lender’s payout into principal, penalty, accrued interest and other charges before entry. Include a charge once. A positive adjustment is a credit; a negative amount is a charge.
Entries are not submitted or saved. Print or save your estimate before leaving or reloading. This tool does not calculate income tax or determine the tax treatment of the property sale. It can show a negative result.
The estimate subtracts all entered expenses, including costs you may pay before closing. Your lawyer’s closing statement may deduct only amounts still payable. Reconcile prepaid expenses and the deposit so neither is deducted twice. The deposit is part of the sale price, not an extra selling expense.
TRREB’s September 2026 Town of Shelburne report recorded 12 sales, an average sale price of $686,624 and a median of $705,750. Sold listings averaged 40 listing days on market. These small-sample municipal results describe the homes sold; they do not establish your home’s value, your fees or how long you will own it before closing.
Source: TRREB September 2026 Dufferin report — Shelburne, PDF page 10. Listing days exclude preparation and negotiated closing time; unsold homes are not represented by the sold-listing average. The PDF cost guide uses planning examples instead of a changing market snapshot.
Ask your lender for a written payout quote before deciding on a listing or closing date. The balance, accrued interest, penalty and discharge or other charges are different lines. A quote may expire or change before closing.
| Mortgage type / timing | Method to check | Cost illustration | Important limits |
|---|---|---|---|
| Closed variable-rate mortgage | Often three months’ interest; contract controls | $1,500–$4,000 | Not a quote or guaranteed range. Ask about privileges, portability and the proposed payout date. |
| Closed fixed-rate mortgage — bank | Often the greater of three months’ interest or interest rate differential (IRD) | $5,000–$25,000+ | IRD compares contract and applicable lender rates; lender methods and contract terms vary. |
| Closed fixed-rate mortgage — non-bank / monoline | Read the lender’s own formula | $1,500–$8,000 | Do not assume a lender category always has the cheaper calculation. Compare written quotes. |
| Open mortgage | Usually no prepayment penalty | $0 penalty | Confirm other payout, administration and discharge charges. |
| Mortgage paid at maturity | Confirm exact date and contract | $200–$400 discharge | Maturity can avoid an early-payout penalty; it does not remove every closing charge or make delayed selling risk-free. |
FCAC guidance on prepayment penalties
Ask about prepayment privileges, portability, maturity and the quote’s expiry. Timing a payout at maturity may avoid an early-payment penalty, but does not remove every charge or establish that waiting will leave you better off.
Kevin explains his approach in this Orangeville example. Discuss the services and cost plan for your own Shelburne property; the video does not document a Shelburne result.
How to Sell Your House for Top Dollar | Kevin Flaherty's Orangeville Marketing Plan
$1,200–$2,000 planning allowance. Ask what the tax-inclusive quote covers, including mortgage discharge work, title and registrations. Retain your lawyer early enough for your transaction.
$200–$400 lender-fee example. Separate it from a prepayment penalty and confirm all related legal and registration charges.
$50–$500 is an illustration, not a cap. A prepaid balance may create a credit; an amount owing may create a charge. The lawyer’s calculation controls.
$50–$300 illustration. Confirm readings, deposits, final bills and any agreement-based adjustments with the provider and lawyer.
$500–$3,000 illustration only. Get a quote based on approval, amount, duration, rate, security and all administration fees.
The standard Ontario status certificate fee is up to $100 including tax. Confirm the property’s legal structure and who will request and pay for required documents.
Choose preparation from the property’s condition, relevant alternatives, available time and quotes. Cleaning, repairs and presentation serve different purposes; do not assume a fixed return or that a pre-listing report will prevent renegotiation.
| Item | Planning example | What to decide |
|---|---|---|
| Professional staging | $1,500–$5,000 | Discuss whether a consultation, occupied-home edit or vacant staging is useful. No automatic 2%–4% premium is assumed. |
| Professional photography | $300–$600 standalone example | Included in Kevin’s package; confirm the agreement and avoid double counting. |
| Video Narrated VR Animated Online Showing | Included in Kevin’s package | Explains the layout and features online. Confirm the service and scope in writing. |
| Pre-listing repairs | $500–$5,000 | Prioritize actual issues with appropriate advice; do not cover damage or assume repairs eliminate later buyer concerns. |
| Deep cleaning | $300–$600 | Choose the required scope; investigate unusual odours or suspected moisture rather than masking them. |
| Landscaping / curb appeal | $200–$2,000 | Address maintenance, entry and safe access; a higher offer is not guaranteed. |
| Pre-listing inspection | $400–$600 | Optional decision support; choose relevant specialists and follow up on findings. Age alone does not determine inspection scope. |
| Storage | $80–$600 | One to three months at the illustrative $80–$200 monthly rate; confirm taxes and access fees. |
Kevin’s Video Narrated VR Animated Online Showings explain layout, features and property information to online buyers. They are included in his listing package; confirm the scope in your agreement. Presentation does not establish a buyer’s financing or guarantee a particular price, fewer conditions or a saving.
A qualifying principal-residence sale may be exempt, but the sale still needs to be reported and designated. Rental, business or mixed use, a second home, short ownership and other facts can change the treatment. The calculator does not determine income tax, recapture or any special property-sale taxes.
| Scenario | Possible treatment | What to review |
|---|---|---|
| Principal residence | An exemption may apply | Eligibility and designation matter. A sale must still be reported and the required principal-residence forms completed. |
| Home partly rented or used for business | Property-specific review | Change-of-use rules, elections, designation years and possible recapture may matter. Do not automatically treat each rental year the same way. |
| Rental / investment property | Tax may be payable | Ask your accountant about capital versus business income, the applicable inclusion rules, deductible expenses and any recapture. A fixed tax percentage is not calculated here. |
| Cottage / secondary property | Review the family’s designation choices | A second property is not automatically covered by the same principal-residence designation for the same year. |
| Property sold within 365 days | Flipping rules may apply | The residential flipping rule can treat profit as business income, with specified life-event exceptions. Holding longer does not itself guarantee capital-gain treatment. |
Ontario land transfer tax generally relates to acquiring land and is paid by the purchaser rather than being a routine seller charge. If you are also buying, budget that separate transaction with your lawyer.
Use the interview guide to discuss services, representation, fees and communication.
10 Questions to Ask Before You Hire a Realtor (Interview Guide)
Compare your lender’s quote for possible closing dates, maturity, privileges and any portable option. Weigh charges against holding costs and selling uncertainty. No universal saving is assumed.
Interest, insurance, utilities, taxes and maintenance can continue until closing. Sold-listing days are not the full ownership period. Separate principal repayment from the cost of borrowing and compare actual cash needs.
Get quotes and compare the expected usefulness, condition issues, delay and cost. No fixed $2–$5 return per dollar or automatic staging premium is built into the budget.
Review the agreed fee, HST, inclusions, representation and estimated net scenarios together. A fee alone does not establish the price, timing or quality of the eventual sale.
Review relevant sold homes, current alternatives and actual search filters with Kevin. There is no universal $25,000 MLS search rule or verified 15%–20% traffic increase for pricing at $799,000 instead of $800,000.
Kevin provides a written net-proceeds estimate before you commit to a listing. Review the sale-price assumption and every cost line. Update the sheet when an offer, date or quote changes; your lawyer’s final statement determines the closing calculation.
Request a Free Shelburne Home EvaluationKevin discusses reasons a listing may stall. Review actual feedback, alternatives, price, access and information before choosing a response.
Pro Real Estate Tips - Why Didn't My House Sell?
These are hypothetical budgets using 4.5% commission plus 13% commission HST. The closing adjustment is assumed to be a charge. Mortgage principal, penalties, bridge financing, personal income tax and unlisted items are excluded. Replace each allowance with your actual figure.
| Sale price | Commission + HST | Legal + discharge | Preparation | Moving | Closing charge | Total |
|---|---|---|---|---|---|---|
| $600,000 | $30,510 | $1,700 | $4,000 | $2,500 | $400 | $39,110 |
| $700,000 | $35,595 | $1,700 | $4,500 | $2,500 | $400 | $44,695 |
| $800,000 | $40,680 | $1,800 | $5,000 | $3,000 | $500 | $50,980 |
| $900,000 | $45,765 | $1,800 | $5,500 | $3,000 | $500 | $56,565 |
| $1,000,000 | $50,850 | $2,000 | $6,000 | $3,500 | $500 | $62,850 |
The $800,000 example totals $50,980. With a $350,000 mortgage principal and no penalty or other added charge, the resulting estimate is $399,020. No table row predicts a sale price or the expenses for a particular home.
Use these 33 checklist tasks across five phases. Preparation windows are planning examples; adapt them to your property and transaction.
There is no single verified local total. Add the agreed commission and its 13% HST, legal and lender charges, preparation, moving and applicable adjustments. Our $800,000 hypothetical sale at 4.5% commission has $50,980 in illustrated selling costs and net charges, before any mortgage penalty or balance. Obtain actual quotes.
Commission is negotiated, not a fixed or approved market rate. The 3.5%, 4.5% and 5% figures here are comparison examples. At $800,000 and 4.5%, commission is $36,000 plus $4,680 HST, for $40,680. Confirm all obligations and included services in your agreement.
Ontario land transfer tax generally relates to acquiring land and is paid by the purchaser, rather than being a routine seller fee. If you are also buying, ask your lawyer to budget the tax on that purchase and consider any applicable exemptions or special circumstances.
Check commission HST, lender penalties and discharge charges, possible cashback repayment, bridge financing, final accounts, closing adjustments and ongoing carrying costs. Include only charges that apply and avoid counting amounts already included in a quote.
Compare the scope, quote, home’s condition and relevant alternatives with Kevin. Staging may help explain rooms and presentation, but a fixed 2%–4% premium, faster sale or positive return is not guaranteed.
A qualifying principal residence may be exempt, but its sale must still be reported and designated. Rental or business use, a second property, short ownership or other circumstances can change the treatment. Have an accountant assess the actual facts and current rules.
Review lender options, choose preparation selectively, compare fees and services, and budget the full period through closing. Use actual quotes and relevant pricing evidence. Kevin’s reported performance figures do not guarantee your own savings or timing.
A net sheet estimates sale price less selling expenses, mortgage payout and net adjustments. It changes as price, dates and charges become known; the lawyer’s final statement establishes the closing calculation. Request Kevin’s personalized estimate through a free home evaluation.
These Dufferin County testimonials describe individual experiences. They do not predict your price, timing or number of showings.
“Kevin's experience and marketing team sold my home over asking price in one day. The house was sold before it even went on MLS. We did not have to go through open houses or multiple viewings. The professional videos his team produces are amazing.”
“The property was listed and sold with second viewing within two days at more than the asking price. The closing dates of this place and the new purchase matched perfectly. Kevin and his team were the epitome of skill and efficiency.”
Kevin reports a 99.2% sale-to-list ratio, approximately 14 average days on market, 52% faster selling and Top 1% in Canada, alongside 30+ years of experience. These are Kevin’s performance statements, separate from the September 2026 Shelburne municipal results. Individual results vary; they do not establish your sale price, timing or savings.
Ask which services are included and compare your actual budget, price assumptions and dates. Kevin’s performance statements should not be used to calculate a guaranteed saving.
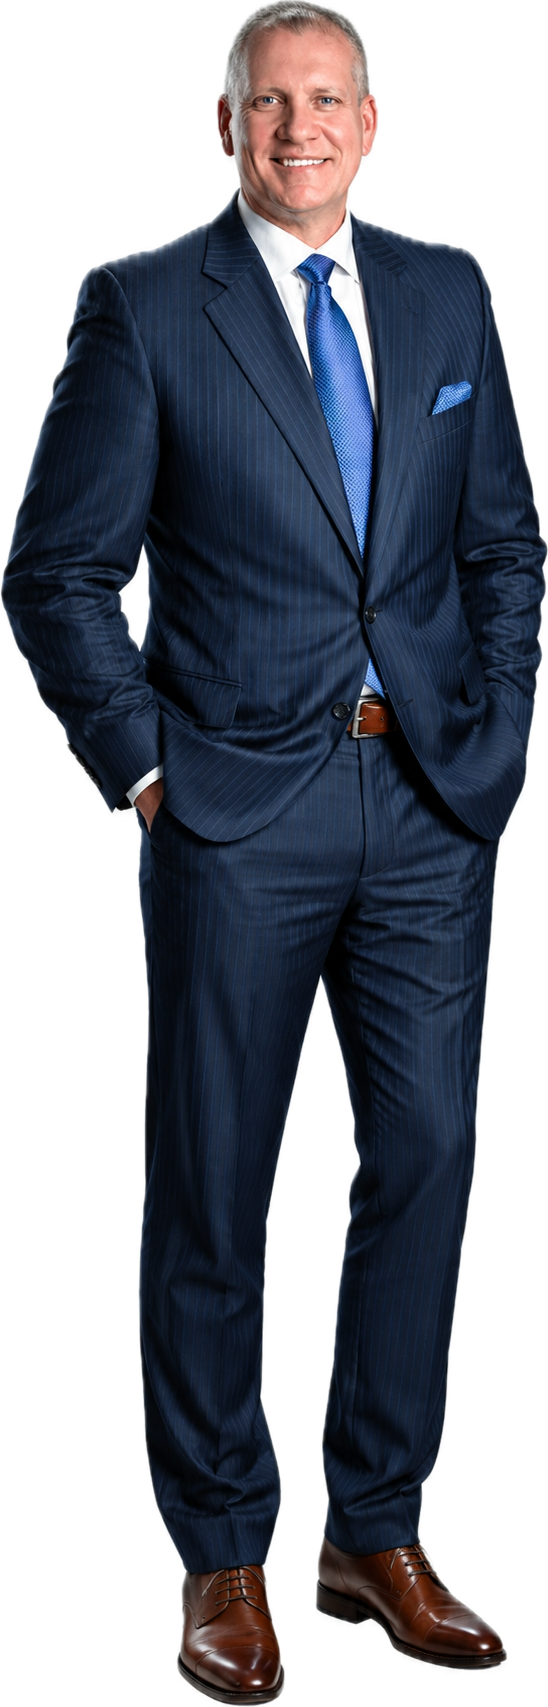
Kevin Flaherty is a real estate broker with experience since 1988, serving Shelburne, Orangeville, Caledon and Dufferin County. His Home Selling System Team uses Video Narrated VR Animated Online Showings, professional photography, floor plans, property websites and online syndication to explain homes to prospective buyers.
Bring your mortgage information, intended timing and preparation questions to a discussion about services, agreed fees and estimated proceeds.
This outline shows the Town of Shelburne municipal area. A nearby rural address may be in another municipality; confirm the property’s actual location and the relevant tax, utility and service authorities. The map is not an office location or legal parcel survey.
Map loading as you approach this section. View the official Ontario boundary source.
Boundary data: Government of Ontario municipal boundaries. Contains information licensed under the Open Government Licence – Ontario. Street map: © OpenStreetMap contributors. This municipal outline is not a neighbourhood, county or legal property boundary, does not establish access rights, and does not identify a Flaherty office location.
Bring your mortgage statement, timing and preparation priorities. Start with a written estimate, then confirm each charge with the relevant professional.
170 Lakeview Court; Unit 3A
Orangeville, ON
L9W 5J7
Not Intended To Solicit Properties Already Listed For Sale.
A HoneyCombHub.ca Web Site Solution
Copyright 2026 . All rights reserved.